Why the challenge of identifying the right investments matters as much as making them bankable.
Two recent developments have got me thinking about how we identify, prepare and invest in infrastructure projects.
At the World Bank Annual Meetings, Ajay Banga highlighted some impressive progress.
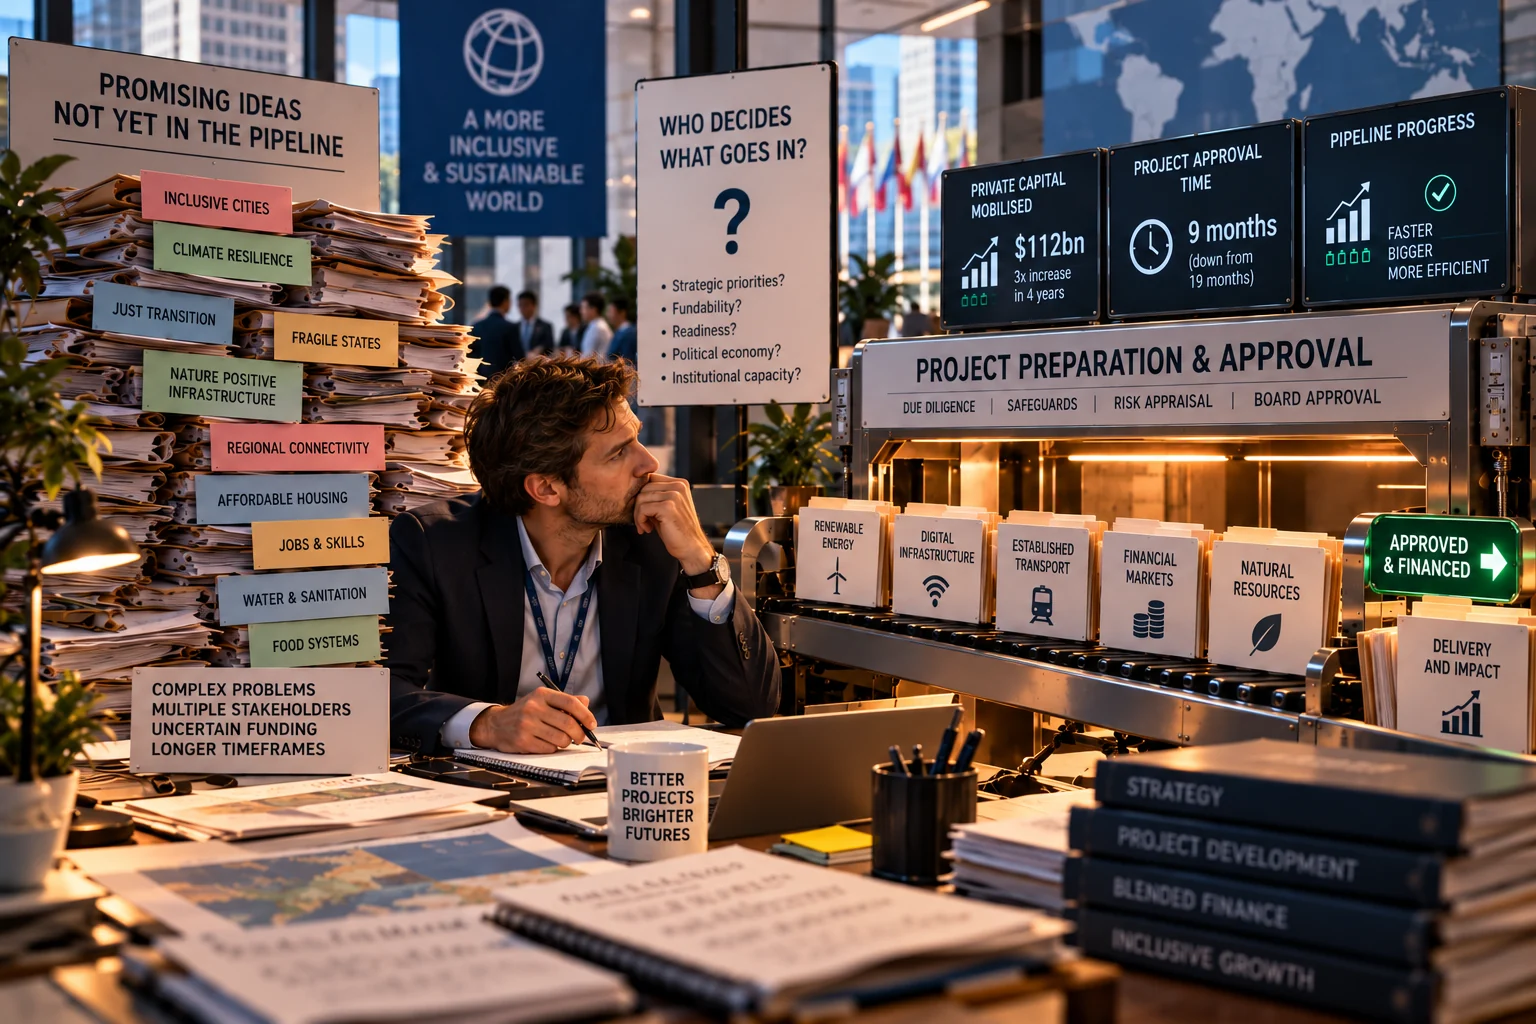
The World Bank Group mobilised $112 billion in private capital last year, more than three times the amount four years ago. Average project preparation and approval times have reportedly fallen from 19 months to nine.
Both are achievements worth recognising.
But look a little deeper, and some interesting questions emerge.
Private capital mobilisation in upper-middle-income countries has more than quadrupled to $50 billion. In lower-middle-income countries it has grown to $37 billion.
Yet in the world's poorest countries, it has remained virtually unchanged at around $3 billion.
And while faster project approvals are welcome, they don't necessarily mean we're reducing the time it takes to develop the most complex projects or resolve the difficult issues that prevent them from progressing.
This isn't to diminish the World Bank's achievements. Mobilising private investment and removing unnecessary bureaucracy are essential.
But it does raise a question about additionality.
If development finance institutions successfully help create functioning investment markets, how do we ensure their continued involvement is delivering something the private sector wouldn't otherwise provide?
And are we devoting enough attention to the harder projects and markets where that support is most needed?
Interestingly, the UK has been grappling with a remarkably similar challenge.
HM Treasury's recent Green Book Review recognised that business cases have too often focused on answering "What is the best way to undertake this project?" rather than "What is the right project to improve growth in this area?"
Think about a local authority.
A town-centre improvement scheme might be relatively straightforward to prepare and deliver. Tackling poor access to employment in disadvantaged communities could require coordinating transport, housing, skills, employers and multiple public bodies.
Both may be worthwhile investments.
But the second is likely to be harder to define, prepare, fund and deliver, even if its potential impact is greater.
Perhaps the real question is: where does a project pipeline actually begin?
We spend enormous effort making existing pipelines investment-ready. And rightly so. Good project preparation is critical.
But what happens before a project enters that pipeline?
Who identifies the problems that most need solving? Who develops the ideas that don't yet have an obvious sponsor, financing model or delivery pathway? And who supports the difficult, cross-cutting projects that might generate the greatest public value?
If we only measure the success of the projects that make it into our pipelines, how do we know what we're missing?
At a recent event I attended, a question was posed: What would we recommend the UK Government include in its 10-year plan, and what should it focus on when hosting the G20 next year?
I keep coming back to this issue.
The UK is reforming how it appraises public investment. The G20 has already developed guidance on preparing investable infrastructure pipelines.
Could we bring those two agendas together and look more seriously at how we identify and develop the right projects in the first place, particularly those that are complex, cross-institutional or focused on inclusive growth?
Not instead of making projects bankable.
But to ensure we're making the right projects bankable.
I'd be interested to hear from colleagues in local government, development finance and infrastructure investment: are there important projects we're failing to progress because they're simply too difficult to get into the pipeline?